

You can feel when confidence starts to slip. Investors ask sharper questions, lenders want more backup, and an accountant in Harrisonburg, VA can help provide the clarity stakeholders need. Board members want cleaner reporting, and employees start reading between the lines. When numbers feel unclear, trust gets expensive. Deals slow down, oversight gets tighter, and every decision carries more tension than it should.
That is where accounting firms matter. Their role is not limited to preparing statements or checking compliance boxes. They help create credibility around the information people rely on to make decisions. How accounting firms contribute to stakeholder confidence comes down to one simple idea. When financial reporting is accurate, consistent, and subject to strong quality controls, people trust what they see and act with more certainty.
Accounting firms strengthen trust through reliable reporting
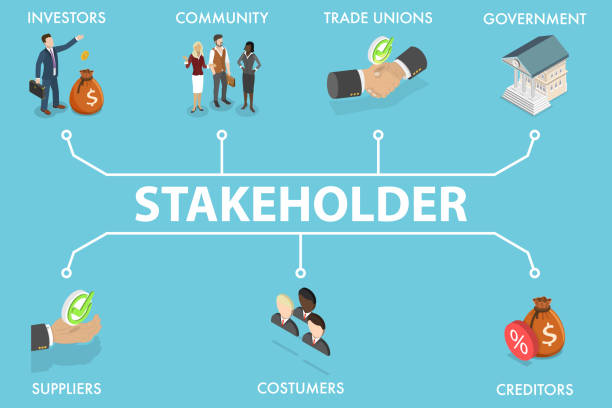
Stakeholders do not all want the same thing, but they all want numbers they can rely on. Investors want a fair view of performance and risk. Lenders want confidence that cash flow and obligations are presented honestly. Regulators want compliance. Boards want information they can use without guessing what may be missing.
An accounting firm supports that trust by testing assumptions, reviewing controls, challenging inconsistencies, and documenting how conclusions were reached. That work reduces the chance that a company presents a picture that looks stable on paper but falls apart under scrutiny.
You see the effect most clearly when the pressure is high. A business may be preparing for financing, managing a leadership change, dealing with rapid growth, or responding to market volatility. In those moments, weak reporting does more than create paperwork problems. It can damage relationships that took years to build. A lender may delay approval. An investor may discount valuation. A board may lose faith in management’s judgment.
Stakeholder confidence in financial reporting grows when an independent accounting firm brings discipline to the process. That discipline tells outside parties that someone with technical standards and professional obligations has taken a hard look at the numbers.
Quality control in accounting firms affects every stakeholder relationship
Trust does not come from a logo on an audit report alone. It comes from the systems behind the work. If an accounting firm has weak supervision, inconsistent review practices, or poor risk assessment, the value of its opinion drops. People may not see those gaps directly, but they feel the results when errors surface later.
The Public Company Accounting Oversight Board has focused heavily on firm quality control. Its statement on the adoption of QC 1000 amendments reflects the push for stronger firm systems that support consistent audit quality. That matters because confidence is not built by one careful professional working in isolation. It is built by a firm-wide structure that supports judgment, review, ethics, and accountability.
The PCAOB also emphasized the need for wider input in its discussion of broader stakeholder perspectives on QC 1000. That approach reflects the reality businesses already face. Financial reporting affects more than management and auditors. It affects pension funds, employees, creditors, and the public markets that depend on credible information.
The SEC has made the same point from the investor protection side. In Paul Munter’s statement on investor protection, the message is clear. Audit quality and professional skepticism are tied directly to market trust. When those standards slip, investors bear the cost first, but the damage spreads far beyond them.
Professional accounting support reduces risk before trust is tested
Problems rarely begin with fraud headlines or restatements. They usually start smaller. Revenue is recognized too aggressively. Estimates are not updated. Documentation is thin. Internal controls exist informally but not in a way that holds up under review. Management may believe everything is fine until a transaction, audit, or financing request forces a closer look.
That is why accounting firm involvement matters early, not only after a problem appears. Strong firms help businesses spot weak processes before they turn into public issues. They bring outside judgment to areas where internal teams may be too close to the facts or too stretched to challenge assumptions thoroughly.
| Situation | Without strong accounting firm support | With strong accounting firm support |
| Loan or financing review | Lenders request repeated clarifications and may delay approval | Financials are easier to defend and credit discussions move faster |
| Investor due diligence | Inconsistencies lower valuation or increase perceived risk | Clear reporting supports credibility and steadier negotiations |
| Board oversight | Directors question reporting quality and management judgment | Directors receive better support for decisions and governance |
| Regulatory scrutiny | Weak documentation increases exposure and remediation costs | Documented processes and reviews reduce avoidable findings |
Clear steps improve stakeholder confidence through accounting practices
Review where trust depends on your numbers. List the groups that rely on your financial reporting, including investors, banks, owners, board members, and key partners. Then identify which reports, disclosures, or controls shape their decisions. This shows where confidence is won or lost.
Test the quality of your reporting process. Look beyond whether reports are produced on time. Ask whether estimates are documented, judgments are reviewed, reconciliations are current, and controls are actually followed. If the process depends too much on one person’s memory or last minute fixes, confidence is already weaker than it appears.
Use outside accounting expertise before a high stakes event. Do not wait for an audit issue, financing round, or regulator inquiry to find gaps. Professional review ahead of those moments gives you time to fix documentation, strengthen controls, and present a more credible picture.
Confidence grows when accounting firms support accountability
Trust is hard to measure until it disappears. Then every missing detail costs more, every delay feels larger, and every explanation sounds defensive. The value of accounting firms is that they help prevent that slide. They support reliable reporting, stronger controls, and the kind of accountability that reassures stakeholders when the stakes are real.
If you are trying to protect investor trust, strengthen lender relationships, or give your board more confidence in the numbers, the right accounting support can steady the ground beneath all of it.
Read more: https://dimensionsscript.com/expert-witness-services-a-cornerstone-in-modern-legal-proceedings/
Zero-Waste, High-Taste: Throw Events That Wow, Not Warm the Planet
2FA for Gamblers: The 30-Second Setup That Saves Your Account

